Arm Holdings (ARM) continues to solidify its foundational role, benefiting immensely from the proliferation of Arm-based NPUs in mobile and edge devices. For its fiscal Q1 2026, Arm reported a 28% YoY surge in royalty revenue, reaching
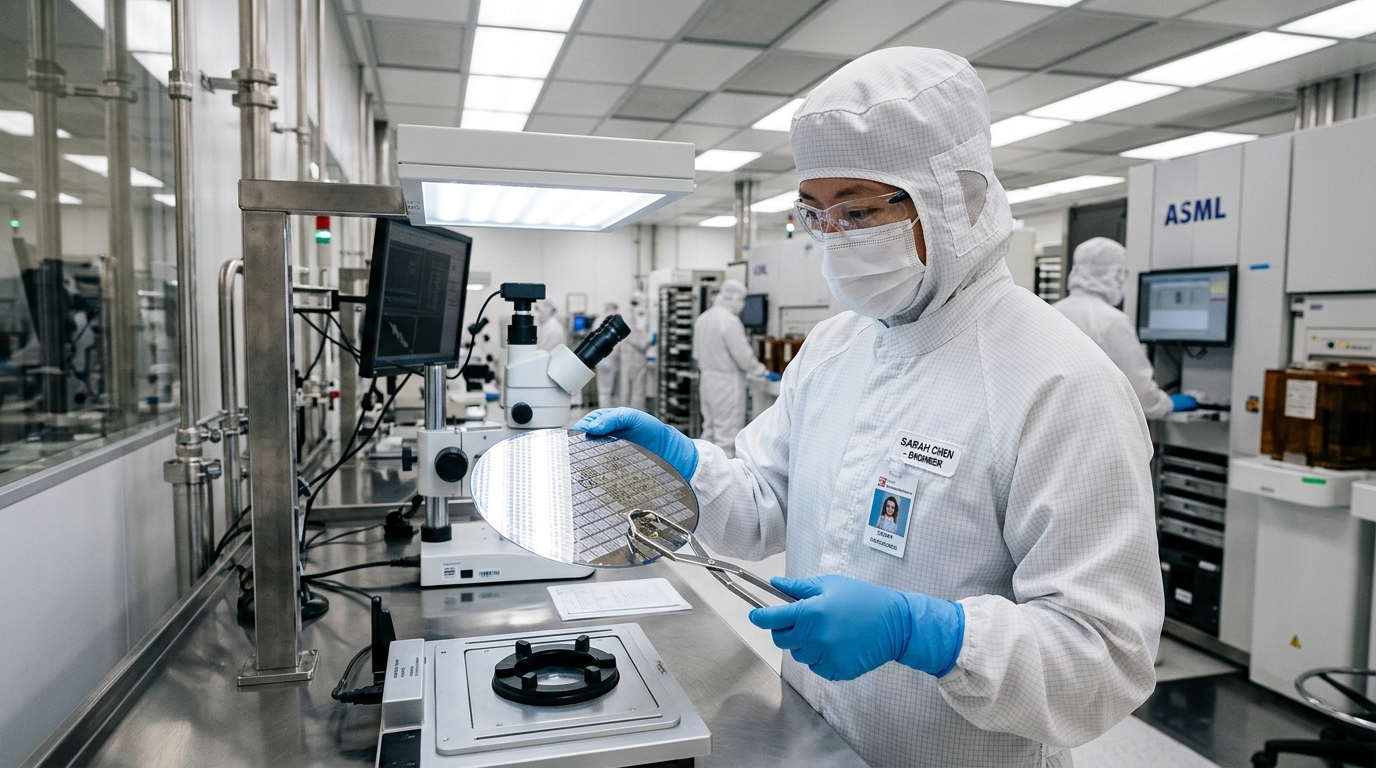
The surge in NPU demand has intensified pressure on advanced foundry capacity, particularly for sub-5nm nodes. TSMC (TSM) has signaled that its 3nm capacity (N3E and N3P processes) is fully booked through Q4 2027, with current utilization rates hovering above 96%. This unprecedented demand, largely from hyperscalers like Microsoft (MSFT), Amazon AWS (AMZN), and Google Cloud (GOOGL) developing custom AI silicon, as well as leading smartphone OEMs, has empowered TSMC to implement a 4.5% price hike for its N3E process in H2 2026, projecting an additional
Memory chip manufacturers are also experiencing a robust upswing. SK Hynix (000660.KS) and Micron (MU) are witnessing unprecedented demand for High Bandwidth Memory (HBM3e), crucial for both data center and increasingly sophisticated edge AI applications. HBM3e contract prices have surged by an average of 22% in H2 2026, with some spot market prices up an astonishing 28% for specific high-density modules. This pricing power is expected to boost SK Hynix's operating profit margin by 600 bps for the second half of the year, while Micron forecasts a 14% sequential increase in memory revenue for its upcoming quarter. While Arm remains dominant in IP, the RISC-V architecture is carving out a significant niche in the edge NPU space, projected to capture 18% of new industrial IoT and automotive NPU design starts by 2027, up from just 7% in 2024. This shift poses a competitive challenge for Arm in specific low-power, high-efficiency applications, although Arm still commands over 90% of the mobile NPU market. From a macro valuation perspective, the sector's Forward P/E multiple currently stands at 35x, a premium to the broader market's 22x, justified by the strong growth narrative and expanding operating margins, which are averaging 28% across the top-tier semiconductor firms.
Analysis of quantitative order flow reveals strong institutional conviction in the continued growth of the Edge AI NPU segment. The 30-day implied volatility (IV) for Nvidia (NVDA) stock options stood at 38.5% as of yesterday's close, significantly above its 1-year average of 32.1%, signaling heightened bullish expectations and demand for upside protection. Furthermore, the call-to-put open interest ratio for ARM Holdings (ARM) options traded on NASDAQ reached an elevated 1.78 this week, notably concentrated in the January 2027
The broader semiconductor sentiment is mirrored in index performance. The KOSPI index, home to memory giants SK Hynix and Samsung Electronics (SMSN.L), has seen a 12.5% appreciation year-to-date, with foreign institutional investors being net buyers of approximately $8.4 billion in Korean semiconductor equities over the last quarter. Similarly, Nasdaq Futures are up 16% since April, partially reflecting the strong performance of technology bellwethers deeply invested in AI infrastructure and edge computing. The SOX Semiconductor Index (SOX) has itself seen a continuous upward trend, closing at 5,420 points yesterday, marking a 1.2% gain on robust volume, with a 3-month average daily trading volume up 25% from the prior period, underscoring liquidity and continued institutional inflows into the sector. Options volume for the SMH ETF has seen its daily average call volume outstrip put volume by a factor of 1.4x over the past 60 days, further solidifying the bullish sentiment.
Tags: Memory Chips, SK Hynix, Semiconductors, Wall Street, Edge AI, NPU, ARM, RISC-V, TSMC, Nvidia