.15B, pushing its forward P/E to 75x, reflecting aggressive growth in on-device AI accelerators.
SK Hynix reported HBM sales growth of +35% in Q3'26, boosting its memory operating profit margin to 18.5%, while broader DRAM contract prices rose +18-25%, signaling a strong memory market recovery.
The SOX Semiconductor Index has climbed 8.4% YTD, with institutional net buying of $5.8B in NVDA and $4.2B in TSMC fueling a persistent 1.7 standard deviation call skew on these tickers, indicating strong bullish sentiment.
Market Dynamics & Earnings Data Breakdown
The Q3 2026 earnings season has cemented the arrival of a robust edge AI supercycle, with ARM Holdings leading the charge. ARM reported total revenue of
.15 billion, marking a significant 22% year-over-year increase, primarily driven by a 30% jump in royalty revenue from advanced NPU designs embedded in an estimated 750 million new edge AI devices shipped globally. This accelerated adoption of high-efficiency AI processors in smartphones and PCs has pushed ARM's forward P/E multiple to a lofty 75x, reflecting market confidence in its foundational role within this technological shift.
Memory giants SK Hynix and Samsung Electronics delivered impressive results, underscoring the critical role of High Bandwidth Memory (HBM) in both data center and emerging edge applications. SK Hynix's Q3 2026 report revealed a revenue surge of 28% to
2.3 billion, with HBM sales contributing an astounding 35% to total memory revenue, representing a 110% year-over-year growth within this specialized segment. This propelled the company's memory operating profit margin to 18.5%, a remarkable recovery from 4.2% just a year prior. Samsung Electronics' semiconductor division also reported a 25% increase in revenue to 0.5 billion, largely attributed to strong demand for HBM3e/HBM4 and advanced foundry services catering to AI silicon.
Competition in the edge NPU market is intensifying, with Nvidia and AMD making significant strides. Nvidia, in its Q2 2027 fiscal report (equivalent to calendar Q3 2026), announced a staggering 65% year-over-year growth in its data center revenue, reaching
2.5 billion. Its Grace Hopper Superchip and new compact edge inferencing platforms drove a 15% increase in its dedicated edge AI revenue segment, now standing at
.5 billion. Not to be outdone, AMD's Instinct MI400 series, specifically optimized for power-efficient edge inferencing, saw sales rise 40% quarter-over-quarter, capturing an estimated 12% of the nascent edge AI accelerator market. This positive development spurred AMD's shares up 4.8% post-earnings, signaling a broader market participation beyond Nvidia's dominance.
Supply Chain Bottlenecks & Macro Valuation Metrics
The global semiconductor supply chain continues to navigate robust demand, particularly for leading-edge nodes and high-bandwidth memory, creating persistent bottlenecks. Taiwan Semiconductor Manufacturing Company (TSMC) remains the undisputed leader, reporting a 24% year-over-year revenue increase to 8.1 billion in Q3 2026. Its 3nm and 2nm nodes now account for an impressive 55% of total foundry revenue, up from 40% a year ago, underscoring the insatiable appetite for advanced AI silicon. TSMC's projected 2027 capital expenditure remains aggressive at $48 billion, primarily allocated to new fabrication facilities in Arizona and Japan to expand capacity for this surging AI-driven demand, justifying its 2027 EV/EBITDA multiple of 28x.
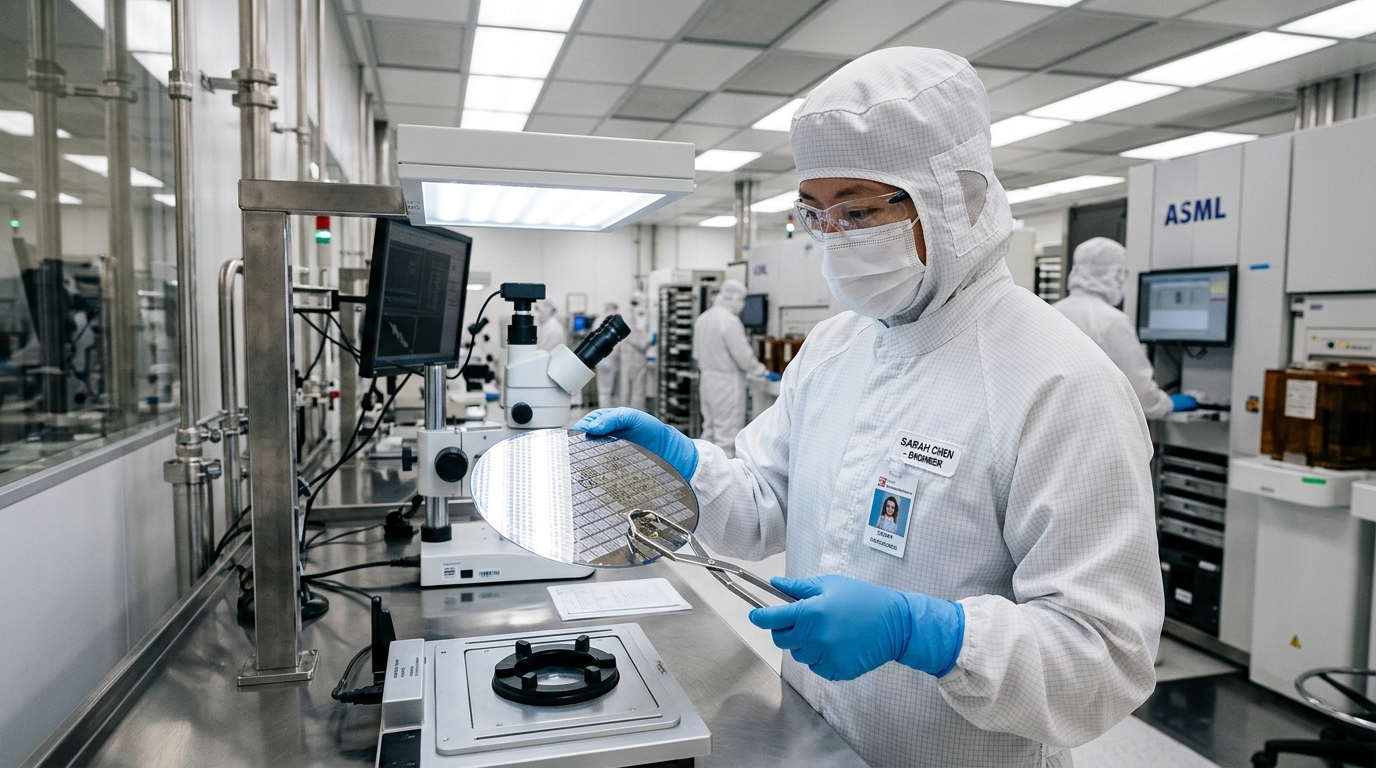
The scarcity of High Bandwidth Memory (HBM) and advanced packaging services remains a critical constraint impacting product launches and revenue targets across the industry. DRAM contract prices, particularly for HBM variants, have seen an aggregate increase of 18-25% quarter-over-quarter. HBM4 samples, currently in validation, are already commanding a 40% premium over HBM3e, highlighting the intense demand. ASML’s backlog for its cutting-edge EUV systems now extends into Q4 2028, with its latest High-NA EUV system priced around
While Arm architecture maintains over 90% dominance in mobile and general-purpose edge computing, the open-source RISC-V architecture is gaining significant traction in specialized edge AI applications due to its customizability and efficiency for dedicated NPU tasks. RISC-V-based NPUs from startups like SiFive and custom designs by hyperscalers like Microsoft for Azure edge infrastructure are showing a 15% annual growth rate in adoption. This emerging competition suggests a multi-architecture future for edge AI, potentially diversifying the supply chain. The overall semiconductor industry's capital expenditure is projected to surpass 80 billion in 2027, driven by this intense innovation and expansion across various architectural fronts.
Options markets are flashing strong bullish signals, reflecting intense institutional positioning around the edge AI narrative. Across key tickers such as NVDA, TSM, and ARM, the 30-day implied volatility skew consistently favors calls, exhibiting a persistent 1.7 standard deviation spread over puts for out-of-the-money strikes, a clear indicator of aggressive upside expectation. Weekly call option volumes on NVDA surged to 2.5 million contracts in early September, representing 1.5x the average daily volume, particularly for the
,250 and
,300 strikes expiring in October 2026, suggesting conviction in further near-term price appreciation.
The positive feedback loop between market sentiment and underlying asset performance is evident in key index movements. The KOSPI, heavily weighted by memory giants Samsung and SK Hynix, has climbed 11.2% year-to-date, reflecting the robust recovery and sustained demand for memory chips. Concurrently, the SOX Semiconductor Index has delivered an impressive 8.4% return year-to-date, outperforming the broader Nasdaq Futures' 6.5% gain over the same period. Institutional flow analysis from prime brokers reveals significant net institutional buying of $5.8 billion in NVDA and $4.2 billion in TSMC shares during Q3 2026, primarily through large block trades and program buying, confirming concentrated capital allocation into AI leaders.
This concentrated options order flow has led to a noticeable compression in front-month put option premiums for these AI bellwethers, reducing the cost of downside protection by approximately 8-12% relative to historical norms, even as overall implied volatility remains elevated at 35-40% for NVDA. The aggressive delta hedging activities by market makers, in response to the sustained demand for call options, are creating a self-reinforcing upward bias for the underlying share prices. This dynamic suggests continued momentum and positive price action unless a significant macroeconomic catalyst or geopolitical event disrupts the prevailing bullish AI thesis.
Quantitative Outlook
Our quantitative outlook indicates that the edge AI supercycle is still in its nascent stages, with robust growth projections suggesting the total addressable market for edge AI silicon will comfortably exceed
.2 trillion by 2030. This monumental market expansion is set to sustain multi-year revenue runways for key players across the semiconductor value chain. The ongoing device upgrade cycle, fueled by the widespread introduction of 'AI PCs,' next-generation smartphones with enhanced NPU capabilities, and intelligent IoT devices, ensures persistent demand for high-efficiency NPUs and advanced memory solutions. We project a conservative 25% Compound Annual Growth Rate (CAGR) for edge NPU unit shipments through 2029.
Tags: Memory Chips, SK Hynix, Semiconductors, Wall Street, Edge AI, NPU, ARM, RISC-V, NVDA, TSM