Front-End Equipment Orders Surge Amid AI Buildout, WFE Forecasts Revised Upward to 50 Billion
Leading wafer fab equipment suppliers report robust orders and raised guidance as AI infrastructure investments drive demand for advanced etching and deposition tools.
Tradesnaut Quant Research Desk · September 21, 2026 · 6 min read · Semiconductors
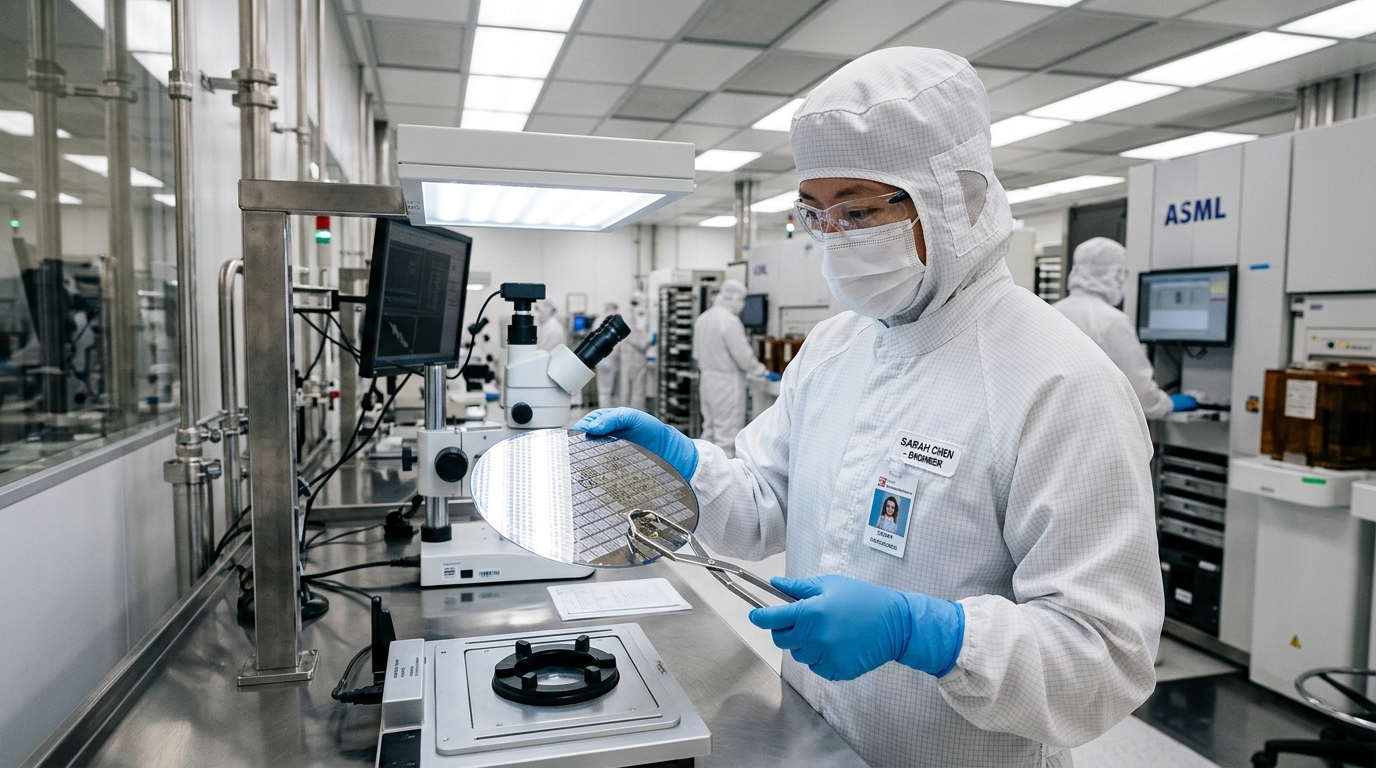 50 Billion" />
Key takeaways
- Wafer Fab Equipment (WFE) spending forecasts for 2026 have been substantially increased, with some estimates now reaching 50 billion.
- The surge is driven primarily by escalating demand for AI infrastructure, necessitating advanced logic, High Bandwidth Memory (HBM), and sophisticated packaging technologies.
- The outlook for toolmakers remains positive into 2027 and beyond, contingent on sustained AI investment and continued capacity expansion efforts by chipmakers.
What changed
Optimism in the front-end wafer fab equipment (WFE) sector has grown notably in recent months, with major industry players and analysts revising their market spending forecasts upwards. KLA Corporation, for instance, updated its calendar 2026 WFE market forecast to "exceed
40 billion" in April 2026, an increase from its prior 35 billion to 40 billion range. This sentiment was echoed by Lam Research, which also adjusted its 2026 WFE estimate to 40 billion with an upward bias at that time. More recently, Goldman Sachs, in an August 2026 research report, sharply raised its global WFE spending forecasts to 50 billion for 2026, 18 billion for 2027, and 81 billion for 2028. This represents substantial increases from earlier estimates, with 2026 up 6%, 2027 up 17%, and 2028 up 35%. Similarly, SEMI announced in July 2026 that the WFE segment is projected to increase 23.1% to 43.9 billion in 2026.
The mechanism
This accelerated demand for front-end equipment is fundamentally driven by the extensive buildout of artificial intelligence (AI) infrastructure. The computational demands of AI necessitate advanced logic, high-bandwidth memory (HBM), and increasingly complex packaging techniques, all of which require cutting-edge wafer fabrication equipment. Chipmakers are investing heavily in technologies like gate-all-around (GAA) transistors, taller NAND stacks, and HBM, which inherently increase the number of etching and deposition steps required during manufacturing. For example, the migration to 2-nanometer (nm) nodes is creating substantial incremental demand for process-control solutions, as highlighted by KLA Corporation. Companies such as Applied Materials (AMAT), Lam Research (LRCX), and KLA Corporation (KLAC) provide the critical tools—etching, deposition, and process control systems—that enable these advanced manufacturing processes. The shift towards stacking multiple dies per package for AI accelerators and HBM demands tighter control over overlay, defectivity, and film thickness, directly benefiting KLA's inspection tools. Moreover, customers are providing longer-term forecasts, with some extending visibility out to 2030, which gives equipment manufacturers greater confidence in future growth.
Who is exposed
The companies at the forefront of supplying front-end wafer fab equipment are directly exposed to this booming demand. Applied Materials (AMAT) reported record revenue of $9.12 billion in Q3 fiscal 2026, up 25% year-over-year, and guided for Q4 fiscal 2026 revenue of
0.25 billion at the midpoint. The company expects its advanced packaging revenues to grow more than 70% in calendar 2026. Lam Research (LRCX) saw its Q3 fiscal 2026 revenue reach $5.84 billion and subsequently reported Q4 fiscal 2026 revenue of $6.72 billion. It guided for Q1 fiscal 2027 revenue of $8.10 billion, plus or minus $400 million, signaling continued momentum. KLA Corporation (KLAC) delivered Q3 fiscal 2026 revenue of .415 billion and provided Q1 fiscal 2027 revenue guidance of $4.0 billion, plus or minus 00 million. KLA also anticipates its process-control revenue from advanced packaging to grow from approximately $635 million in calendar 2025 to roughly billion in 2026. The broader semiconductor industry, including leading-edge foundry/logic and memory manufacturers, is benefiting from these investments, but the equipment makers are the primary beneficiaries of the increased capital expenditure.
Quantitative Outlook
The market data for these key players reflects the strong demand. Applied Materials (AMAT) recently traded at 443.55, with a volume of 14,302,926. Lam Research (LRCX) closed at 288.44, seeing a volume of 19,636,004. KLA Corporation (KLAC) finished at 177.15, with a volume of 20,072,505. These figures, available in the market data table below, align with the positive earnings and guidance reported by the companies. The NASDAQ Composite index, which includes many semiconductor firms, also shows positive momentum, rising 0.39% to 26,523. The upward revisions to WFE spending forecasts by multiple firms, including Goldman Sachs' projection of
50 billion for 2026 and even higher for subsequent years, suggest that the current investment cycle is far from over. Critical to sustaining this trajectory will be continued hyperscale data center investments and the accelerating pace of AI innovation. Any slowdown in AI development or a significant shift in capital expenditure priorities by leading chip manufacturers could alter the current optimistic picture. However, with leading-edge foundry logic, DRAM, and advanced packaging expected to drive approximately 80% of WFE growth in 2026 and 2027, the underlying demand appears structurally robust for the foreseeable future.
Tags: Semiconductors, WFE, Applied Materials, Lam Research, KLA Corporation, AI
Leading wafer fab equipment suppliers report robust orders and raised guidance as AI infrastructure investments drive demand for advanced etching and deposition tools.
Tradesnaut Quant Research Desk · September 21, 2026 · 6 min read · Semiconductors
50 Billion" />
Key takeaways
- Wafer Fab Equipment (WFE) spending forecasts for 2026 have been substantially increased, with some estimates now reaching 50 billion.
- The surge is driven primarily by escalating demand for AI infrastructure, necessitating advanced logic, High Bandwidth Memory (HBM), and sophisticated packaging technologies.
- The outlook for toolmakers remains positive into 2027 and beyond, contingent on sustained AI investment and continued capacity expansion efforts by chipmakers.
What changed
Optimism in the front-end wafer fab equipment (WFE) sector has grown notably in recent months, with major industry players and analysts revising their market spending forecasts upwards. KLA Corporation, for instance, updated its calendar 2026 WFE market forecast to "exceed
40 billion" in April 2026, an increase from its prior35 billion to40 billion range. This sentiment was echoed by Lam Research, which also adjusted its 2026 WFE estimate to40 billion with an upward bias at that time. More recently, Goldman Sachs, in an August 2026 research report, sharply raised its global WFE spending forecasts to50 billion for 2026, 18 billion for 2027, and 81 billion for 2028. This represents substantial increases from earlier estimates, with 2026 up 6%, 2027 up 17%, and 2028 up 35%. Similarly, SEMI announced in July 2026 that the WFE segment is projected to increase 23.1% to43.9 billion in 2026.The mechanism
This accelerated demand for front-end equipment is fundamentally driven by the extensive buildout of artificial intelligence (AI) infrastructure. The computational demands of AI necessitate advanced logic, high-bandwidth memory (HBM), and increasingly complex packaging techniques, all of which require cutting-edge wafer fabrication equipment. Chipmakers are investing heavily in technologies like gate-all-around (GAA) transistors, taller NAND stacks, and HBM, which inherently increase the number of etching and deposition steps required during manufacturing. For example, the migration to 2-nanometer (nm) nodes is creating substantial incremental demand for process-control solutions, as highlighted by KLA Corporation. Companies such as Applied Materials (AMAT), Lam Research (LRCX), and KLA Corporation (KLAC) provide the critical tools—etching, deposition, and process control systems—that enable these advanced manufacturing processes. The shift towards stacking multiple dies per package for AI accelerators and HBM demands tighter control over overlay, defectivity, and film thickness, directly benefiting KLA's inspection tools. Moreover, customers are providing longer-term forecasts, with some extending visibility out to 2030, which gives equipment manufacturers greater confidence in future growth.
Who is exposed
The companies at the forefront of supplying front-end wafer fab equipment are directly exposed to this booming demand. Applied Materials (AMAT) reported record revenue of $9.12 billion in Q3 fiscal 2026, up 25% year-over-year, and guided for Q4 fiscal 2026 revenue of
0.25 billion at the midpoint. The company expects its advanced packaging revenues to grow more than 70% in calendar 2026. Lam Research (LRCX) saw its Q3 fiscal 2026 revenue reach $5.84 billion and subsequently reported Q4 fiscal 2026 revenue of $6.72 billion. It guided for Q1 fiscal 2027 revenue of $8.10 billion, plus or minus $400 million, signaling continued momentum. KLA Corporation (KLAC) delivered Q3 fiscal 2026 revenue of.415 billion and provided Q1 fiscal 2027 revenue guidance of $4.0 billion, plus or minus 00 million. KLA also anticipates its process-control revenue from advanced packaging to grow from approximately $635 million in calendar 2025 to roughlybillion in 2026. The broader semiconductor industry, including leading-edge foundry/logic and memory manufacturers, is benefiting from these investments, but the equipment makers are the primary beneficiaries of the increased capital expenditure.Quantitative Outlook
The market data for these key players reflects the strong demand. Applied Materials (AMAT) recently traded at 443.55, with a volume of 14,302,926. Lam Research (LRCX) closed at 288.44, seeing a volume of 19,636,004. KLA Corporation (KLAC) finished at 177.15, with a volume of 20,072,505. These figures, available in the market data table below, align with the positive earnings and guidance reported by the companies. The NASDAQ Composite index, which includes many semiconductor firms, also shows positive momentum, rising 0.39% to 26,523. The upward revisions to WFE spending forecasts by multiple firms, including Goldman Sachs' projection of
50 billion for 2026 and even higher for subsequent years, suggest that the current investment cycle is far from over. Critical to sustaining this trajectory will be continued hyperscale data center investments and the accelerating pace of AI innovation. Any slowdown in AI development or a significant shift in capital expenditure priorities by leading chip manufacturers could alter the current optimistic picture. However, with leading-edge foundry logic, DRAM, and advanced packaging expected to drive approximately 80% of WFE growth in 2026 and 2027, the underlying demand appears structurally robust for the foreseeable future.Tags: Semiconductors, WFE, Applied Materials, Lam Research, KLA Corporation, AI