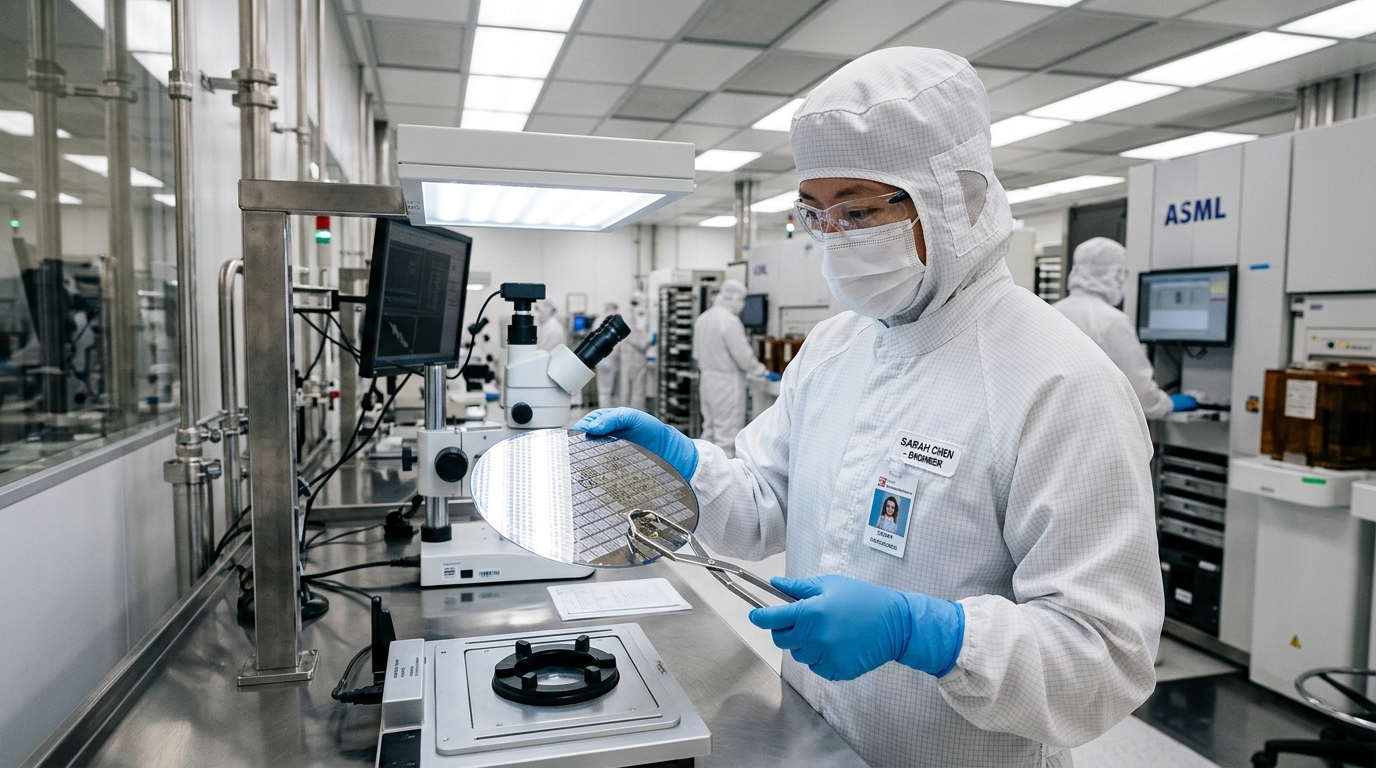
However, the continued reliance on advanced lithography tools from firms like ASML (ASML) remains a critical bottleneck for China's true independence. Despite stringent export controls, ASML reported a +14.8% year-over-year increase in revenue from China for H1 2026, totaling .85 billion, primarily stemming from the sale and servicing of DUV (Deep Ultraviolet) machines for mature nodes (28nm and above) which remain outside the most restrictive sanctions. This flow of equipment, while not directly enabling 5nm production, allows Chinese foundries to build out significant capacity for automotive, IoT, and industrial applications, indirectly freeing up domestic capital and engineering talent to focus on more advanced processes. The overall semiconductor industry's EV/EBITDA multiple has slightly compressed to 18.5x from 19.8x at the beginning of the year, reflecting increased geopolitical risk premiums, with Chinese domestic foundries like SMIC still trading at a premium of 40x forward earnings, indicative of the perceived growth potential within a protected market.
Institutional capital flows are visibly shifting, with a net
Options market activity for key semiconductor players reflects heightened uncertainty surrounding the US-China tech rivalry and the accelerating pace of China's self-sufficiency. For TSMC (TSM), the 30-day implied volatility surged to 38.5% on August 29, up from 31.2% a week prior, with the put-to-call ratio jumping to 1.35, indicating a significant bearish skew as traders bought protection against further downside. Notably, the weekly options chain for September 6, 2026, saw a massive block trade of 25,000 contracts for
Conversely, options on Micron Technology (MU) showed a more balanced, albeit still elevated, implied volatility of 42.1%, with a call-to-put ratio of 0.95. This suggests speculative interest in a potential rebound if global memory demand remains robust, but also considerable caution regarding the long-term competitive threat from CXMT. The KOSPI index, a bellwether for South Korean chipmakers, declined -3.2% in the last week, dragged down primarily by Samsung Electronics (005930.KS) and SK Hynix (000660.KS) which collectively represent over 25% of the index's weight. The Philadelphia Semiconductor Index (SOX) experienced a -3.5% drop over the same period, shedding 165 points, signaling a broader sell-off across the sector, with institutional net selling across SOX-tracking ETFs reaching $850 million over the past five trading days.
Analysis of dark pool trading data reveals a net institutional selling of .3 billion in US-listed semiconductor equities over the last three weeks, primarily concentrated in high-valuation growth stocks like Nvidia (NVDA) and AMD (AMD), albeit with smaller percentages of their overall trading volume. This suggests profit-taking and re-allocation rather than a complete exit, as investors navigate the evolving geopolitical landscape. While large technology companies like Meta (META) and Google (GOOGL) continue to invest heavily in custom AI chips and domestic fab partnerships, providing some counter-cyclical demand, the overwhelming options flow skew indicates a prevailing risk-off sentiment towards traditional foundry and memory providers directly impacted by China's aggressive localization strategy, amplifying perceived long-tail risks across the supply chain.
The current market environment, characterized by China's accelerated chip self-sufficiency and persistent US export controls, necessitates a nuanced quantitative approach to semiconductor positioning. Tradesnaut Intelligence maintains a cautiously bullish long-term outlook for the global semiconductor sector, forecasting a compound annual growth rate (CAGR) of 9.2% through 2030, driven by AI and IoT demand, but acknowledges significant near-term volatility. We project that while SMIC (00981.HK) may experience continued domestic market share gains, its ability to scale 5nm production efficiently without advanced ASML EUV tools will cap its global market penetration to below 5% for advanced logic by 2028. Its current forward P/E of 40x already prices in substantial growth and is vulnerable to any deceleration in yield improvements or further tightening of equipment access.
Tags: Memory Chips, SK Hynix, Semiconductors, Wall Street